
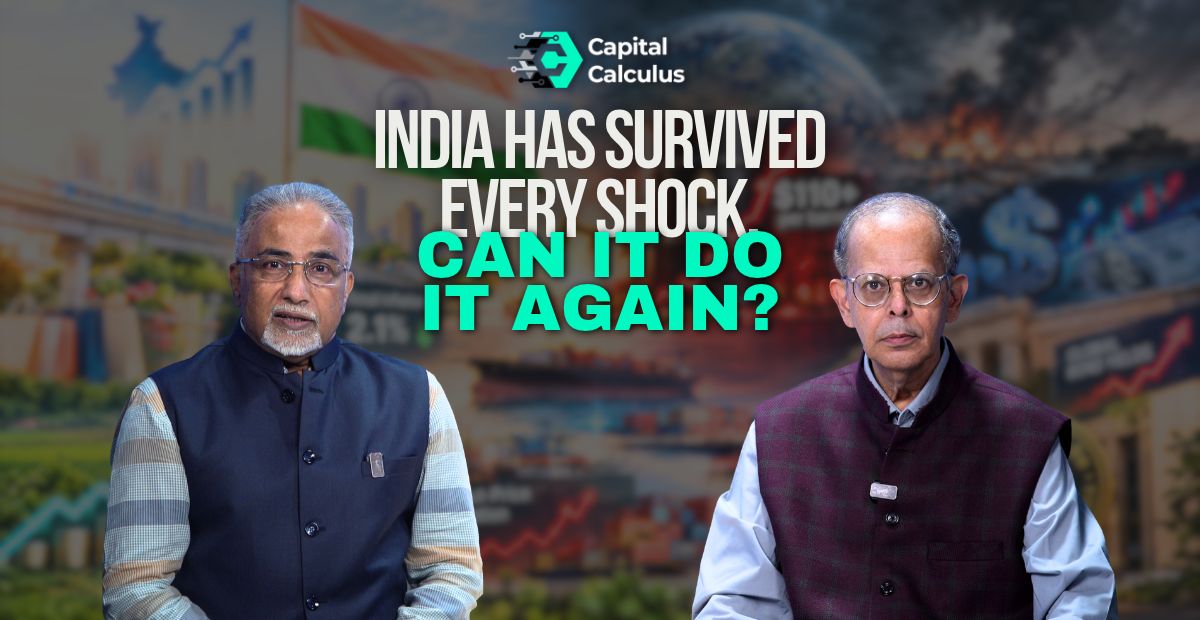
In February, in India entered the latest crisis in the Middle East from a position of strength—with 7.4% GDP growth and a moderate retail inflation at 2.1%.
But the global macro environment has since become more difficult. Oil crossed $110 a barrel, the dollar is strengthening, global bond yields are rising and geopolitical risks are multiplying. In India, inflation is edging higher and is just shy of 5%, while input-price inflation is already much higher.
Can India’s newly acquired resilience absorb another global shock?
And what does this mean for growth, the rupee, inflation and the RBI’s next policy move?
To answer all this and more, StratNewsGlobal.Tech spoke to Saugata Bhattacharya, former Chief Economist at Axis Bank and a member of the RBI’s Monetary Policy Committee.
Saugata also discussed an important emerging trend: whether India’s resilience, until now largely powered by consumption, is beginning to broaden to include private investment—potentially giving India two engines of growth as it flies into a perfect storm.

